PROPERTY INVESTMENT LOANS · MELBOURNE & GEELONG
Think beyond
the next purchase.
Your first investment or the next property in your plan. Let’s look at the lending, the ongoing costs and the room you want to keep for life.
Phone, video or office appointment. You can start with questions.
Where are you up to?
IF YOU’RE RESEARCHING
A property needs a plan around it.
Before you focus on a loan amount, make space for these three conversations.
-
The role of the investment
Be clear about your goals, likely holding period and the risks you are willing to carry. FRF can discuss lending; independent advice can help you assess the property and wider investment decision.
See how a conversation starts → -
Cash flow beyond the rent
Allow for vacancy, repairs, rates, insurance, management and any owners corporation costs. Rent and property values can fall; neither is a guaranteed source of growth.
Plan repayments and buffers → -
Equity and your wider plans
Accessing equity means taking on borrowing, not receiving free cash. Ask how the extra commitment could affect a future home move, family plans or business funding.
Understand equity borrowing →
WHEN YOU’RE READY TO TAKE A STEP
Build a picture you can discuss.
A realistic lending conversation starts with the whole household and property picture, including the less comfortable scenarios.
-
Bring the property and cost estimates
Include the proposed price, buying costs, a rental estimate and ownership costs. Identify who provided each estimate and what still needs checking.
Get the investment worksheet → -
Test the room in your budget
Consider a period without rent, a repair bill or a rate rise. Decide what cash buffer you want to keep and discuss how much shortfall your household could manage.
Explore repayment scenarios → -
Check the loan and the property separately
Lender approval does not establish that a property is a good investment. Obtain appropriate property, legal and tax advice alongside the finance assessment.
Review property checks →
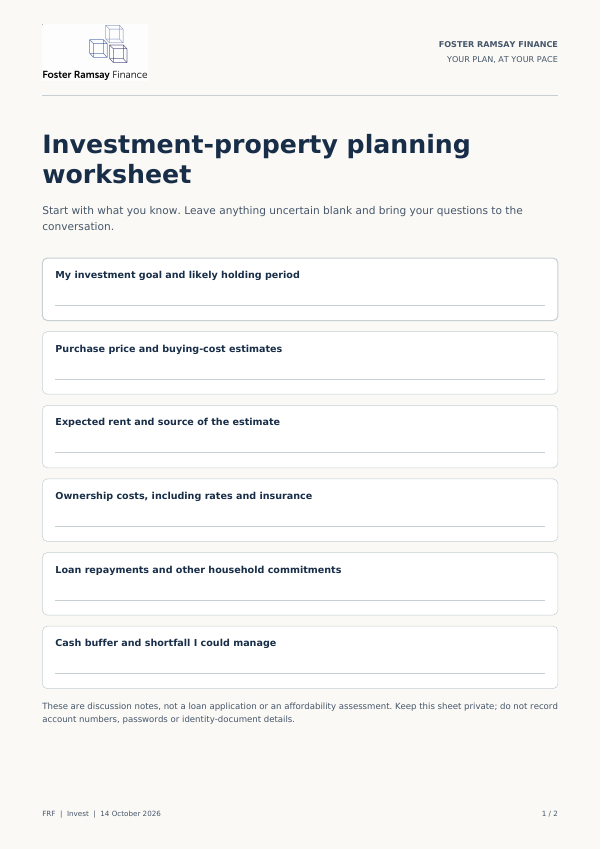
A USEFUL FIRST STEP · FREE DOWNLOAD
Investment-property planning worksheet
Bring the purchase, ownership costs and loan questions together. There are no assumed returns: use your own estimates and mark what needs professional advice.
- Purchase costs and ongoing commitments
- Vacancy, repairs and cash-buffer prompts
- Security, repayment and tax questions
2-page PDF · 184 KB · No email required. Print and complete by hand.
Can I use equity for an investment deposit?
It may be possible, subject to valuation, lender policy and your ability to repay the additional debt. Compare how the borrowing is secured and what it means for your existing home and other plans.
Will rent cover the loan?
It may not cover the loan and all ownership costs, and there may be periods without a tenant. Use a realistic budget and test how you would fund a shortfall.
Can FRF tell me which property to buy?
Our role here is to help with the lending conversation. Property selection, investment performance, legal issues and tax treatment need the appropriate separate advice. We do not promise rental returns or capital growth.
LET’S TALK IT THROUGH
Bring the plan behind the property.
Talk with Chris about the lending, your commitments and the choices you want to keep open.
Ringwood / Melbourne · Geelong · Phone & video
General information only, not an approval or a recommendation for your circumstances. Lending criteria, terms, fees and eligibility apply. Seek appropriate legal, tax and financial advice for your decisions.
Sources and information checked · 14 October 2026
- Moneysmart: buying an investment property ↗
- Australian Taxation Office: rental-property interest expenses ↗
- Moneysmart: using a mortgage broker ↗
Rules and products can change. Confirm current requirements before acting. Lender examples explain features and are not product recommendations.