SME FINANCE · VEHICLES & EQUIPMENT
Finance for the way
your business works.
A work vehicle. Equipment that saves time. Room for the next stage. Let’s start with what your business needs and the cash flow behind it.
Phone, video or office appointment. You can start with questions.
Where are you up to?
IF YOU’RE RESEARCHING
Give the funding a clear job.
You don’t need to arrive knowing the product name. Start with the outcome you want.
-
Keep the business moving
If cash comes in after expenses fall due, map the gap and how it will be repaid. Short-term timing needs call for a different discussion from funding an ongoing loss.
Explore working-capital options → -
Put an asset to work
Bring the vehicle or equipment quote, how it will be used and when you need it. Consider its useful life alongside the finance term and any final payment.
Explore asset finance → -
Plan the next stage
Explain what the investment is intended to achieve. Your cash-flow forecast should show the commitments the business would need to carry, including a slower period.
Prepare a funding brief →
WHEN YOU’RE READY TO TAKE A STEP
Bring a clear brief, even if it’s a first draft.
We can help identify the information a lender will need. You can start with the purpose and the questions you haven’t resolved.
-
Purpose, amount and timing
Summarise the purchase or business need, the funds you can contribute and the date that matters. Add quotes or invoices where you have them.
Download the funding brief → -
The financial picture
Be ready to discuss trading history, income, expenses, existing commitments and forecasts. Required records vary; we’ll agree what to provide and a secure way to share it.
Prepare for your conversation → -
The people and obligations
Clarify the borrower, proposed security, any guarantees and the effect on personal plans. Ask your accountant and legal adviser about structure, tax and guarantee obligations.
Also planning a home loan? →
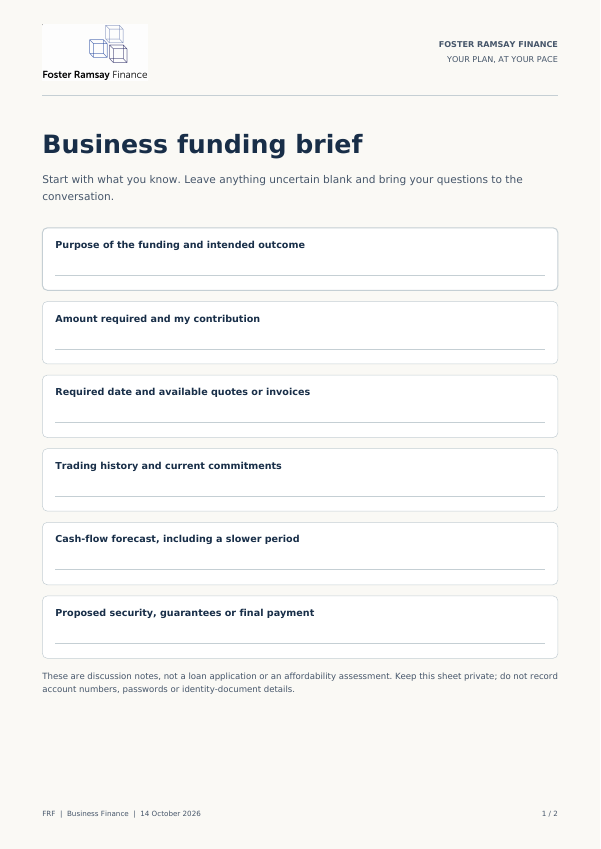
A USEFUL FIRST STEP · FREE DOWNLOAD
Business funding brief
Explain the purpose in plain English, then bring together the amount, timing, cash flow and questions. A useful starting point for you, Chris and your accountant.
- Purpose, amount and purchase timing
- Cash flow and existing commitments
- Security, guarantees and final payments
2-page PDF · 184 KB · No email required. Print and complete by hand.
Can I talk before I have all the documents?
Yes. Start with the purpose, amount and timeframe. We can explain the information likely to be needed. The lender will still require evidence before making its assessment.
Does unsecured mean there is no personal risk?
No. A personal guarantee may still be required, and the borrower remains responsible for the debt. Read the facility and guarantee documents and obtain independent legal advice about the obligations.
Will business finance affect a future home loan?
It can. Business and personal commitments, income, security and guarantees may be relevant to a home-loan assessment. Tell us about both plans early so the discussions can be connected.
LET’S TALK IT THROUGH
Tell us what you want to make possible.
Bring the business need. Chris can help you explore the funding questions and the practical next step.
Ringwood / Melbourne · Geelong · Phone & video
General information only, not an approval or a recommendation for your circumstances. Lending criteria, terms, fees and eligibility apply. Seek appropriate legal, tax and financial advice for your decisions.
Sources and information checked · 14 October 2026
- business.gov.au: preparing for a business loan ↗
- ANZ: business overdrafts (product example) ↗
- ANZ: unsecured business loans and guarantees (product example) ↗
- NAB: vehicle and equipment finance (product example) ↗
Rules and products can change. Confirm current requirements before acting. Lender examples explain features and are not product recommendations.